The MNL Ski Team has been in action again: Chile 2025. Please click the image below…

“There is a tide in the affairs of men…” Shakespeare.
“What’s actually going to happen is rich people are going to use AI to replace workers.” “It’s going to create massive unemployment and a huge rise in profits. It will make a few people much richer and most people poorer. That’s not AI’s fault, that is the capitalist system.” “We don’t know what is going to happen, we have no idea, and people who tell you what is going to happen are just being silly,” he adds. “We are at a point in history where something amazing is happening, and it may be amazingly good, and it may be amazingly bad. We can make guesses, but things aren’t going to stay like they are.” Geoff Hinton.
“AI is fundamentally transforming Oracle and the rest of the computer industry, though not everyone fully grasps the extent of the tsunami that is approaching,” Larry Ellison.
Factsheet Commentary

For our full Factsheet, link here.
Q2 Results Season
NVDA. Revenue jumped 56% Y/Y to $46.7 billion ($0.6 billion beat). The growth continues…
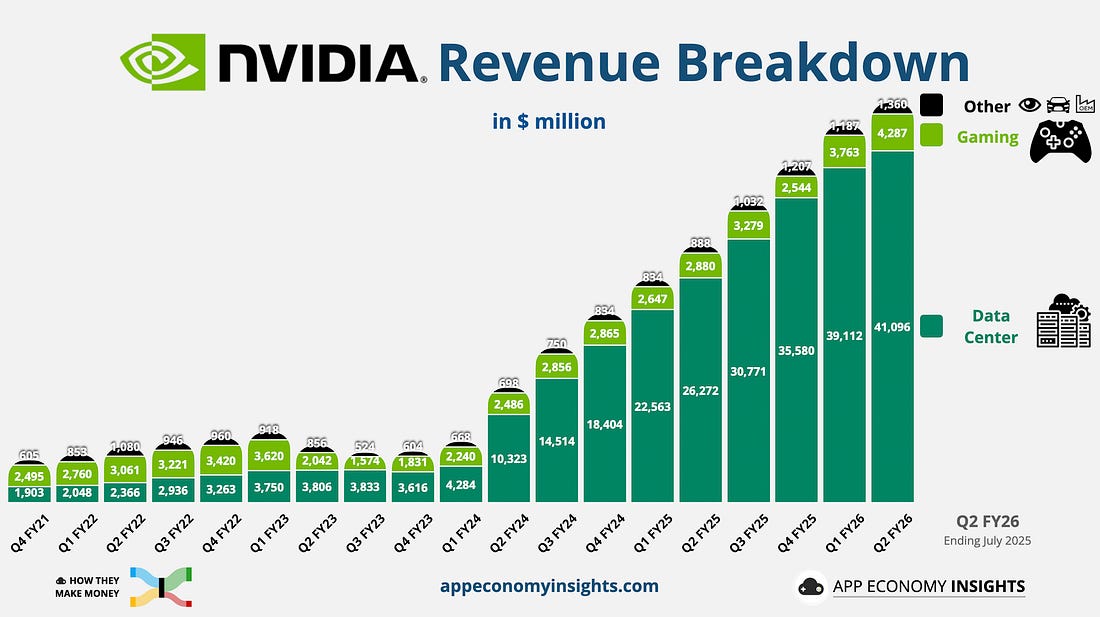
We often stress how we like stocks with elite financial metrics. Check these out:
- Gross margin was 72%.
- Operating margin was 61% (-1pp Y/Y).
- Free cash flow was $13.5 billion which is a 29% margin.
- Cash and cash equivalents are now $56.8 billion, and a similar sized stock buy back scheme has been announced.
Key points:
“Over the next 5 years, we’re going to scale […] into effectively a $3 to $4 trillion AI infrastructure opportunity. The last couple of years, you have seen that CapEx has grown in just the top four CSPs has doubled to about $600 billion. So we’re in the beginning of this build-out.”
The TAM expands from Hyperscaler to NeoCloud to Sovereign to Enterprise….
“Sovereign AI is on the rise as the nation’s ability to develop its own AI using domestic infrastructure data and talent presents a significant opportunity for NVIDIA. […] We are on track to achieve over $20 billion in sovereign AI revenue this year, more than double that of last year.”
…and it gets better with time…
“NVIDIA’s software innovation combined with the strength of our developer ecosystem has already improved Blackwell’s performance by more than 2x since its launch. Advances in CUDA, TensorRT-LLM, and Dynamo are unlocking maximum efficiency.”
“New NVFP4 4-bit precision and NVLink 72 on the GB300 platform delivers a 50x increase in energy-efficiency per token compared to Hopper, enabling companies to monetize their compute at unprecedented scale. For instance, a $3 million investment in GB200 infrastructure can generate $30 million in token revenue, a 10x return.”
The shift to complex “agentic AI” is a fundamental driver of growth…
“Chatbots used to be one shot, you give it a prompt and it would generate the answer. Now the AI does research. It thinks and does a plan, and it might use tools. It’s called long thinking […] The amount of computation necessary for one shot versus reasoning agentic AI models could be 100x, 1000x, and potentially even more.”
As Jensen says: “We’re in every cloud for a good reason. Not only are we the most energy efficient, our perf per watt is the best of any computing platform. And in a world of power-limited data centers, perf per watt drives directly to revenues.”
…so we move to the era of Blackwell (NVIDIA’s Blackwell platform reached record levels, growing sequentially by 17%) and there is lots to be excited about: CoreWeave’s blog highlights that NVIDIA’s BG300 NVL72 instances, featuring Blackwell Ultra GPUs, deliver over six times the raw throughput per GPU compared to the H100, enabling faster and more efficient AI token generation. Full stack with networking and software offers a best in class combination of performance, versatility and efficiency and, as yet, no competitor is close. Some would argue they never will close the gap…
“We’re on an annual cycle […] because we can do so to accelerate the cost reduction and maximize the revenue generation for our customers. […] Our next platform, Rubin, is already in fab.”
In addition, NVDA is building new markets in simulation, vision, quantum and robotics. The future is incredibly exciting.
“The age of physical AI has arrived, unlocking entirely new industries in robotics, industrial automation. Every industry and every industrial company will need to build two factories, one to build the machines and another to build their robotic AI.”
China:
NVIDIA’s own guidance assumes the worst…
“We have not included H20 in our Q3 outlook […] If geopolitical issues reside, we should ship $2-to-$5 billion in H20 revenue in Q3. […] We continue to advocate for the US government to approve Blackwell for China.”
We would hope that the Sales to China over the next 12m will surprise on the upside. Many say the Chinese can approximate NVDA with their home grown Chip Technology, but we very much doubt that they can and we would be surprised if the Chinese want to get left too far behind in modelling.
Conclusions:
Morgan Stanley: “with the stock trading at about 26.5 times projected 2027 non-GAAP earnings and a low PEG ratio, making it an attractive investment in the AI semiconductor space. The price target was raised slightly to $210. Overall, NVIDIA is viewed as the best risk/reward opportunity among large-cap AI companies, with accelerating revenue and earnings growth, improving margins, and strong demand for AI computing power. The company continues to execute well despite external uncertainties, particularly related to China.”
AppEconomy: “NVIDIA’s moat is a fortress built on four walls: CUDA software, its ubiquity across clouds, its unmatched systems and networking integration, and its superior performance-per-watt in a power-limited world. Frontier models are better precisely because they “think longer,” with queries requiring an exponential number of tokens. As more tasks shift from humans to AI, the world is not going to look back. There will always be a new leading-edge model tapping more into NVIDIA’s ability to deliver accelerated computing.”
Beth Kindig: “Looking forward, what I am dubbing as “Nvidia 3.0” will be the shift from 8-GPU server-scale systems to 72-GPU rack-scale systems — which is augmented with the back-to-back release of Blackwell and Blackwell Ultra. Nvidia’s new rack-scale systems will mark one of the most significant turning points in its history. Regardless of what market participants think about Big Tech’s surging capex spend, the spend will continue to rise as those who get the NVL72 systems (that are beginning to ramp now) will have a critical advantage over those still on the HGX or DGX systems with 8 GPUs. Nvidia’s Stock Can Reach $6 Trillion Market Cap by Next Year.”
DELL. “We’ve now shipped $10 billion of AI solutions in the first half of FY26, surpassing all shipments in FY25,” Chief Operating Officer Jeff Clarke said in the statement. Clarke said the company now expects to ship $20 billion in servers by the end of the fiscal year.
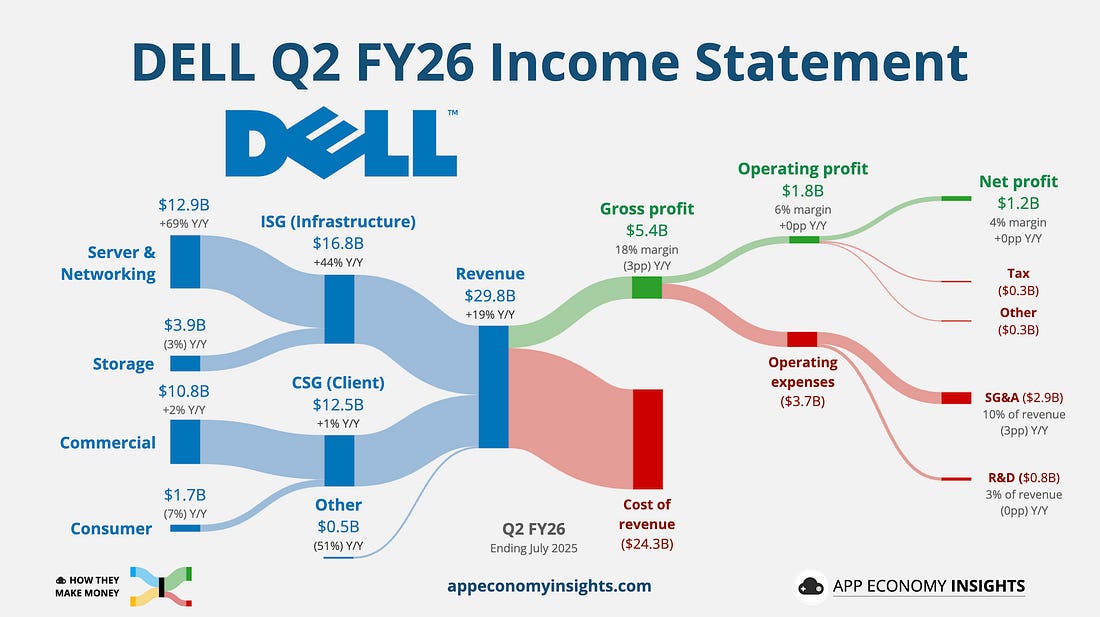
Dell raised full-year FY26 guidance to ~$107 billion of revenue ($4 billion raise), and now expects about $20 billion of AI server shipments this year. Q3 guidance of ~$27 billion in revenue and about $2.45 EPS was more mixed, as AI order intake cooled from Q1 and margins remain a watch item. Even so, demand for AI infrastructure remains exceptional, with growing shipments and a sizable backlog supporting second-half momentum.
“We continue to see strong demand for AI servers, building on the exceptional demand observed in Q1. We booked $5.6 billion in orders in the second quarter and shipped a record $8.2 billion, resulting in an ending backlog of $11.7 billion. For context, we have shipped more AI servers in the first half of this year than all of last. Our five quarter pipeline continued to grow sequentially with double-digit growth across enterprise and sovereign opportunities. Our pipeline remains multiples of our backlog. Enterprise orders and our buyer base grew sequentially in Q2 distributed across various industries such as financial services, healthcare and manufacturing…Our innovation engine is firing in all cylinders and the opportunity is showing no signs of slowing down.”
DELL does not have elite financial metrics but it does have Michael Dell, the opportunity of the Era and it undertakes Buy Backs, so we will ride the stock whilst the infrastructure build out continues.
AVGO. AI-related revenue surged 63% Y/Y to $5.2 billion, beating estimates. More importantly, guidance for AI semiconductor revenue in Q4 is $6.2 billion, well ahead of the ~$5.8 billion consensus. Broadcom’s Q4 revenue guidance of $17.4 billion sailed past the ~$17.0 billion consensus. The biggest news came from CEO Hock Tan, who revealed a new major AI customer (reportedly OpenAI) with over $10 billion in orders, promising a “significant” acceleration in AI revenue for FY26.
AVGO is our 3rd largest holding, so clearly we believe it has excellent opportunities from the Era of Ai, but NVDA is positioned to grow as a full-stack accelerated-computing platform company across simulation, robotics, and hybrid quantum software, while Broadcom’s growth is more concentrated in supplying the underlying AI infrastructure, being custom silicon, high-speed networking, optics, and enterprise virtualization through VMware. The opportunity sets are different in scope and mix and, ultimately, scale.
Besides, NVDA is now fighting back against AVGO:

CELH update post the new equity stake deal with Pepsi.
We like the growth opportunities for Celsius, if Celsius matches the growth of the zero sugar energy drink market (7.2% CAGR), without gaining share, its revenue will grow from an expected $2.4bn in 2025 to ~$3.4bn by 2030. We think it will gain share.
We also guess that there is a compelling argument that people will substitute other forms of caffeinated drink for zero sugar energy drinks, as we have at our office. So if we layer on a conservative substitution case, with Celsius capturing just 1% of the $285bn ready-to-drink tea & coffee and cola market by 2030, that implies $2.85bn of incremental revenue, taking CELH’s total Sales in 20230 to $6.25bn, a ~21% CAGR from 2025, versus the consensus at 11%.
This excludes any upside from international expansion, pricing and mix, or additional share within energy.

HOOD, what’s the story?
The total retail investor assets under administration is estimated to compound at an 8% CAGR to 2030. Assuming the top U.S. and UK retail brokers’ (IB, Charles Schwab Retail , IG, HL, AJ Bell, Interactive Investor, Etoro, CMC invest, Trading 212 UK) revenue pool compounds at the aforemnetioned 8%, and Hood captures 25% of that pool by 2030, HOOD’s revenue gets to roughly $11bn. This explicitly excludes Vanguard, Fidelity and E*TRADE, who we think will also bleed clients to HoOOD over time, due to HOOD’s exciting new product development pipeline.
Then we need to add in the huge potential of prediction markets, or Event Contracts. Global sports betting gross gaming revenue is forecast to reach ~$190bn in 2030, which implies ~$2.4T of handle on an 8% hold. If prediction markets take 20% of that handle, charge 1¢ on the dollar, and HOOD wins 25% share, that’s about $1.2bn from sports. Kalshi volume skews ~70% sports today; with Robinhood’s investor-centric base we modestly assume ~50% sports, implying a similar haul from non-sports (rate cut bets, election results etc.), which lifts total prediction-market revenues to ~$2.4bn.
Drawing all this together, we hope for 2030 revenue of about $12.4bn vs the $3.5bn current run rate which implies a ~28% CAGR from 2025–2030, comfortably ahead of the street at 22% CAGR. The best way to assess the stock is to try the product. We have and we are impressed.
The State of Ai.
Following our Newsletter last month, we were asked about the appeconomyinsights.com diagrams that we post in the Results season sections above. I noted that this weekly email encourages me because it shows all the S&P500 companies with low margins and huge overheads that we are NOT invested in. However, the most exciting element of my weekly review is that this unproductiveness is the feast of the future that makes up the TAM for Ai. We would point you towards these overheads being the opportunity for Ai. Ai is not primarily a tool to leave overheads the same, and to double Sales. Ai is a tool which will remove overheads, increase margins and drive productivity.
The Denialists have been out in force since our Last Newsletter. I suggest a quick read of this article: The Peculiar Persistence of the AI Denialists
https://yaschamounk.substack.com/p/the-peculiar-persistence-of-the-ai?utm_medium=ios
…in the meantime, the Brokers are forecasting further growth…

…and the growth is being driven by Thinking Time…and the effect on Tokens…
Basic chatbot Q&A: 50 to 500 tokens;
Short document summary: 200 to 6,000 tokens;
Basic code assistance: 500 to 2,000 tokens;
Writing complex code: 20,000 to 100,000+ tokens;
Legal document analysis: 75,000 to 250,000+ tokens;
Multi-step agent workflow: 100,000 to one million+ tokens.
There is strong evidence suggesting that the pace of Ai capability improvement is non-linear, and we believe investors are under-appreciating this dynamic with agentic AI task duration (a proxy for complexity and capability) doubling every 7 months…or materially reducing costs…

Robotics

General Market Investing
…every Newsletter, that we write we pray for lower 10YR yields…

…and now it is starting to look like the US is the best house in a bad neighbourhood…

…with rates coming down, we see the SPX grinding higher and see ~15 – 20 per cent upside by the end of 2026…but September or October are often prone to dramas…

…but MKTs love buy backs and U.S. share buybacks are expected to accelerate beyond this year’s record $1.5 trillion pace, potentially adding another $600 billion in the coming years.

Key Manchester & London Updates
As for MNL…apparently everyone is terrrified we are off to buy an insurance vehicle…


…which has flushed out some of our US holders who have sold our stock. Believe me, I am struggling to find the time to cut my toe nails never mind venture into Insurance.
A surprise for some shareholders are our holdings in CELH, FWONK or HOOD as these are not obvious Technology holdings. So may we remind you that we are classified as a Global Growth Fund as is shown in the snip below from Citywire’s website (who we believe to be the best Fund Rating company).

Key Tweets of the Month
Which valuations are crazy….

…besides there is a long way to travel yet…so are you sure you should be selling now?

So the old ways will die…if the humans don’t mess it up…

…even the Denialists have confused themselves…


…in the meantime, their Value darlings look unwell…

The Long Portfolio

Please watch out for China exposures in Technology portfolios…


PDMRs, Buy backs & the Discount

China, the Tech Wars and the forthcoming War of Taiwan in 2027


Please remember that the best way to way to follow our day-to-day thinking is on our Twitter handle: https://twitter.com/MLCapMan

<td valign=”top”
Subscribe to our Newsletters
Each month we share the risks & opportunities we are watching across markets.